Idaho Copper models US$1.88B CuMo value with US$1.17B initial cost
The preliminary study relies on molybdenum credits, while the release gives no tungsten output target or revenue contribution.
 Theo Marchetti
Idaho Copper Corporation NYSEAMERICANCOPR reported on Wednesday that an updated preliminary economic assessment valued its CuMo project in Idaho at US$1.88 billion after tax over a 46-year mine life. The Oct. 14 study summary estimates US$1.17 billion in initial construction capital and another US$658 million for an expansion in year five.
The developer describes CuMo as a copper-molybdenum-silver project that also contains tungsten and rhenium. Its release gives no tungsten production target, recovery estimate or separate revenue contribution, while management attributes the project's by-product cost advantage to molybdenum.
Shares were lower at US$2.92 on NYSE American at 9:35 a.m. EDT on Oct. 14, according to the NYSEAMERICANCOPR quote.
Idaho Copper targets completion of a prefeasibility study in 2028 and has made no decision to construct CuMo. The preliminary economics partly rely on inferred mineral resources, and no mineral reserves have been estimated.
Smaller Plant Reduces Initial Capital
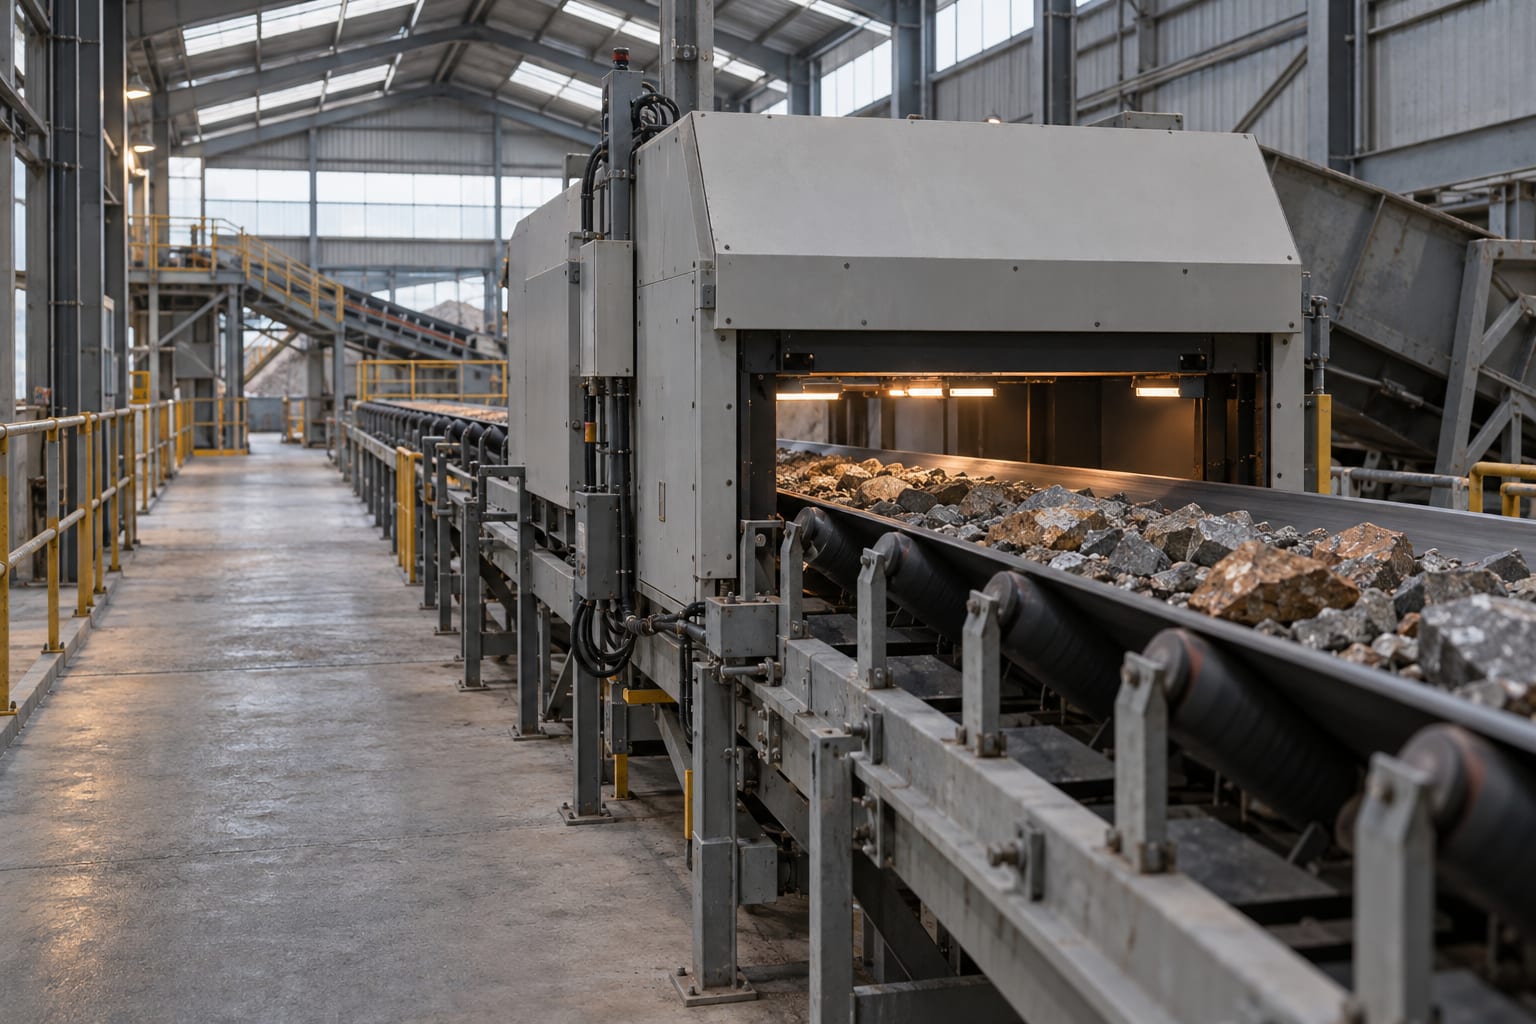
The updated plan uses a smaller first-phase plant, X-ray fluorescence ore sorting before milling and a mining sequence intended to reach higher-grade material sooner. It will supersede the company's 2020 PEA, although the announcement does not give a comparable earlier capital figure.
"Starting with a smaller plant and sorting the ore before it reaches the mill means we need materially less capital up front, with a rapid payback driven by ore sorting," chief executive Andrew Brodkey said in the release.
The Oct. 14 base case uses an 8 per cent discount rate and estimates an 18.5 per cent after-tax internal rate of return. Payback is modelled at 5.9 years from the start of production.
The Oct. 14 price assumptions are US$5 a pound for copper and US$25 a pound for molybdenum. Silver is modelled at US$50 an ounce.
Average annual production over the first 21 years is forecast at 41.6 million pounds of copper and 30.5 million pounds of molybdenum. The plan also forecasts 1.36 million ounces of silver annually over that period.
The Oct. 14 summary puts copper C1 cash costs at negative US$4.30 a pound after by-product credits. This non-GAAP measure excludes initial and expansion capital, so it does not measure the full cost of building the mine.
Release Does Not Quantify Tungsten Output
A comparison comes from Guardian Metal Resources plc LONGMET NYSEAMERICANGMTL OTCMKTSGMTLF, whose June 2026 prefeasibility study forecasts 15,916 tonnes of tungsten trioxide in concentrate from Pilot Mountain in Nevada. Its planned mine life is eight years.
Read more: Allied Critical Metals gains EU strategic status for Borralha tungsten
Idaho Copper's announcement does not disclose updated resource tonnage, grades, cutoff or the resource estimate's effective date. The company says a study summary and technical report will be filed on Form 8-K with the SEC, with a corresponding technical report on SEDAR+.
Pilot-scale test work is intended to validate the ore-sorting assumptions at commercial scale; the release gives no completion date for those tests. Most prefeasibility work is planned for 2027, ahead of the targeted 2028 completion that would provide the next study of CuMo's economics.